Why this is worth having
Credit limit = 90% of your FD amount
750+ CIBIL score achievable
Welcome benefits worth ₹5,000+
Offers on Your Favourite Brands
Upto ₹250* off on Bookmyshow
Upto ₹1,000* off on Amazon
Upto ₹1,50* off
on
Zepto
Upto ₹₹100* off
on
Swiggy
Get your card in 4 simple steps
Keep your documents ready
PAN card, Aadhaar card, nominee details, and bank account details
Enter your applicant details
Fill in your personal, income, and address information
Create your Fixed Deposit
Start with a minimum FD of ₹2,000 and pay via UPI or net banking
Complete your video KYC
Quick call with
SBM Bank · 9am–11pm.
Enjoy the benefits within 2 days.
Frequently Asked Questions
What is the FD-Backed Credit Card?
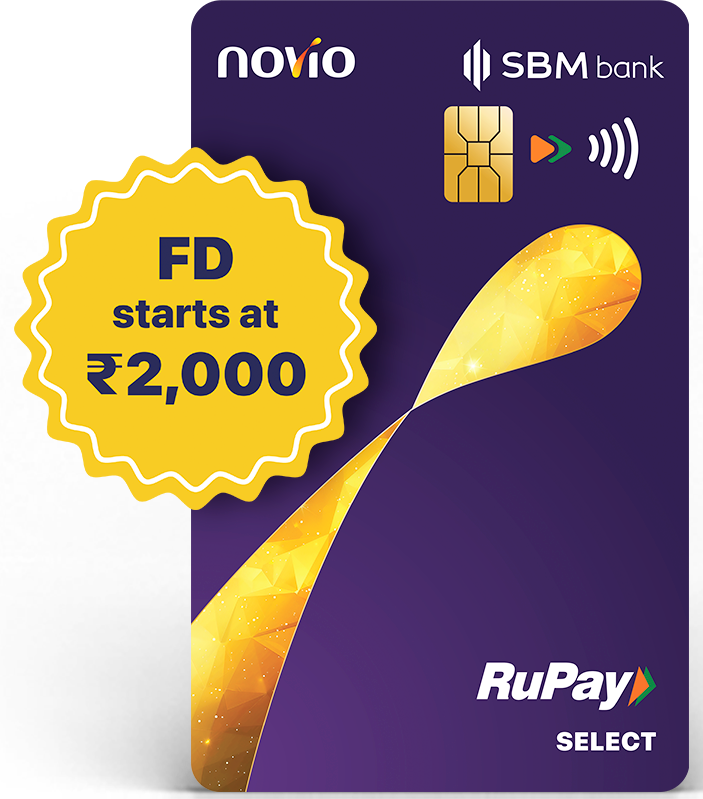
The FD-Backed Credit Card (FD CC) is a RuPay SELECT credit card backed by a Fixed Deposit with SBM Bank India. Users place a minimum FD of ₹2,000 and receive a credit limit of 90% of that FD value — so a ₹2,000 FD gives a ₹1,800 credit limit. The card is issued by SBM Bank India and powered by Novio, a fintech application by Credilio. Lxme facilitates access to the product for its users.
Who issues the credit card and the Fixed Deposit?
Both the Fixed Deposit and the credit card are issued by SBM Bank India (State Bank of Mauritius India), a licensed, RBI-regulated scheduled commercial bank. Deposits are insured up to ₹5 lakhs under DICGC. The card management and rewards experience are powered by Novio (Credilio). Lxme's role is limited to facilitating user access — we are not a bank, NBFC, or card issuer.
What is LXME's relationship with Credilio and SBM Bank?
Lxme works with Credilio as an affiliate partner, giving Lxme users access to the FD CC through a seamless in-app journey. Credilio's platform (novio) powers the application flow and card management. SBM Bank India is the regulated entity that issues the card and holds the FD. Lxme facilitates the product — it does not issue cards, hold deposits, or take any financial risk.
Who can apply for the FD CC?
Any Indian citizen above 18 years with a valid PAN and Aadhaar can apply. Users from the following states/UTs are currently excluded:
- Assam, Arunachal Pradesh, J&K, Ladakh, Tripura, Manipur, Meghalaya, Mizoram, Nagaland, and Sikkim
What is the minimum FD amount? Is there a maximum?
The minimum FD is ₹2,000, which gives a credit limit of ₹1,800 (90% of the FD). The maximum FD via UPI is ₹1 lakh; up to ₹5 lakhs is accepted via other payment modes. To receive a physical card, the FD must be above ₹10,000. Below that, users get a digital card only, which can be linked to UPI apps for everyday spending.
What credit limit do users get?
Users receive a credit limit equal to 90% of their FD value. For example, a ₹5,000 FD gives a ₹4,500 credit limit. The FD itself continues to earn 6.5% p.a. interest throughout the card's tenure, so the user's money is not idle.
What are the fees associated with the card?
The card is lifetime free — there is no joining or annual fee. Other applicable charges:
- ATM cash withdrawal: 2.5% of the amount or ₹299, whichever is higher
- Late payment fee: ₹499
- Forex markup: 2.49%
- Card replacement: ₹249
- Cancellation within first year: ₹599
How does a user apply for the FD CC on LXME?
The journey is entirely digital and happens within the Lxme app:
- User sees a banner or popup on the LXME app and taps on it
- Mobile number and email are verified via OTP
- PAN and Aadhaar are verified with CKYC consent
- User selects their FD amount and pays via GPay, PhonePe, or bank account
- Application form is filled (personal, income, address, nominee details)
- User accepts the MITC, KFS, and FD terms
- Video KYC (VKYC) is completed via a short video call with an SBM Bank official (available 9am–11pm)
- Digital card is activated within 24–48 hours; physical card arrives in 5–7 business days
How does the user access and use the card after it is issued?
The digital card is available immediately in the novio app after VKYC approval. Users can link it to UPI apps (PhonePe, Google Pay, BHIM) as a RuPay credit card for everyday payments. The physical card, once received, is activated using the code in the card kit and can then be used across UPI, online, and POS transactions.
What does the ₹20,000 savings claim mean?
₹20,000 is the total value a user can unlock by availing all welcome benefits and ongoing offers available on the card. This is an aggregate figure across all platforms and benefit types — it represents the maximum possible value if a user actively claims every available offer over time.
What are the key benefits and offers on the card?
Welcome and ongoing benefits include:
- Amazon: Up to ₹1,000 off per month (slab-based: ₹100 off on ₹2,000; ₹250 on ₹5,000; ₹500 on ₹10,000; ₹1,000 on ₹20,000)
- Zepto: ₹50 off on orders above ₹499, up to 3 times a month
- BookMyShow: Up to ₹250 off (min. 2 tickets, transaction ≥ ₹500)
- Swiggy: ₹100 off per month
- Welcome benefits worth ₹5,000+ from 10+ brands including HPCL, Trends, Ajio, Soch, and Pharmeasy
- novio coins on every spend: 5% back on all transactions, 10% on fuel — redeemable at Amazon, Myntra, Domino’s, KFC, McDonald’s, Puma, and 10+ others
Why did LXME launch this product?
Lxme's core audience — first-generation women investors including homemakers, business owners, gig workers, and first-time earners — often lack a credit history. This is a structural gap, not a personal failing: many of them have simply never had a formal financial product in their name. An FD-backed credit card is the most accessible entry point into the credit system. It requires no income proof, no prior credit history, and no existing score — just a minimum FD of ₹2,000. At the same time, the FD earns 6.5% p.a. interest, so users grow their savings while building their credit profile.
How does the FD CC help users build a credit score?
Every transaction made using the card — whether on UPI, online, or at a point-of-sale — is reported to credit bureaus. Regular, responsible use of the card over time builds the user's CIBIL or Equifax score. This opens the door to better financial products in the future, including unsecured personal loans, higher credit limits, and more competitive interest rates.